

OpenAI has officially announced that the frontier AI company will be going public, with plans to IPO in the not too distant future. The company provided some remarks:
“We recently submitted a confidential S-1. We expect it to leak so we’re just announcing it. We have not decided on timing yet; it may be a while because there are things we want to do that are likely easier as a private company. But it’s a complicated set of tradeoffs and this gives us the option to go public sooner if that ends up being best.”
— OpenAI’s X Account, June 8, 2026
Within this statement, OpenAI explicitly states that “there are things we want to do” which are likely easier to complete as a private company – this is an interesting statement. What could OpenAI be up to that would necessitate such a delay?
Let’s put a pin in that subject for a moment, and shift gears to look at the industry holistically.
Welcome to IPO Season.
It has finally become ‘mega-corp’ IPO season, with the likes of Anthropic, SpaceX and finally, OpenAI all filing SEC paperwork with the roadmap to IPO this year. Now, this news may not be a surprise to some – on the other hand, valuations have turned heads. However, I encourage you to look past the valuations, and grapple with the idea of something more ‘tactical’ happening within the under-current inside the shadow of multi-trillion dollar headlines.
SpaceX was first to do something that caught my eye. Upon IPO, SpaceX has secured the right to acquire the AI-first IDE company called Cursor for roughly $60 billion USD. This follows news of SpaceX also acquiring Elon Musk’s other start-up, xAI (Grok + X Platform) for a massive $250 billion USD. Thus, making SpaceX not only a frontier space company, but also a compute-ready, artificial intelligence company that is poised to compete with OpenAI and Anthropic.
This sequence of events should not go unnoticed. The tactical investor will look at these moves and start to pick up on the undercurrent developing in front of them. This SpaceX IPO isn’t just a space company breaking ground, but rather the first frontier AI company emerging into the public domain – and they are generating material revenue.
SpaceX’s Revenue Profile:
xAI: ~$3.2 billion ARR
Cursor: ~$3 billion ARR
SpaceX: ~$12 billion ARR
This is now becoming a battle of the ‘most viable’ and revenue generating frontier company. Both Anthropic and OpenAI will now need to justify their hefty IPO valuations, by generating expansive annual revenues of their own. This is critical if they ever want to be considered for the S&P500 and Nasdaq 100. The question is, how?
Well, for Anthropic this issue has been addressed recently, with their clear expanse into the enterprise domain – ramping Claude-powered tools including code CLI capabilities, design applications, and collaborative enterprise workspaces. The adoption has been impressive to witness, and their target audience is quite large. This trajectory builds in a predictable revenue source from reliable enterprise and business clientele – this is something investors can definitely appreciate.
On the other hand, even though OpenAI has developed enterprise/business applications like Codex – the company has taken a different path than Anthropic. They’ve targeted the consumer. If you recall, OpenAI was the first model to release back in 2022, soaking up most of the consumer audience – of which still today utilizes ChatGPT as their core daily AI tool of choice. Now, this is interesting – because, if we look to adjacent industries we can spot some parities:
Alphabet (Google): Consumer Focus
OpenAI: Consumer Focus
Microsoft: Enterprise Focus
Anthropic: Enterprise Focus
I couldn’t help but notice this similarity. Obviously the comparison is a surface level observation, but you don’t need to go much deeper to notice something important. Microsoft and Anthropic both are focusing on the business or enterprise – these revenues tend to be sticky, contract-bound, with a high-degree of business lock-in. On the other side of the coin, is Google and OpenAI – these companies have both targeted the consumer as their core audience. The question is, how has Google generated reliable revenue from its core consumer audience?
The answer is Advertising.
OpenAI’s Solution.
Enter Zeta Global.
If you haven’t figured it out yet, advertising will be a pivotal high-margin line of business for OpenAI moving forward. OpenAI dominates the consumer lane – with 54.7% of all consumer AI search activity originating from their ecosystem. Advertising will become a core pillar of OpenAI’s business model – in fact, management knows this. Let’s circle back to where I put a pin in the original conversation – what is it that OpenAI alluded to when they said “there are things we want to do that are likely easier as a private company.”?
Here are my thoughts.
What has made Google, Meta, and more recently Amazon successful in advertising is a robust demand-side platform (DSP). OpenAI announced a few months ago that they are developing their own DSP, and are in the process of vetting partners that could help fulfill their ad-platform success. Speculation from ‘The Information’ theorized AppLovin and TheTradeDesk were both considered as strong candidates. Although both were reportedly considered, neither was selected.
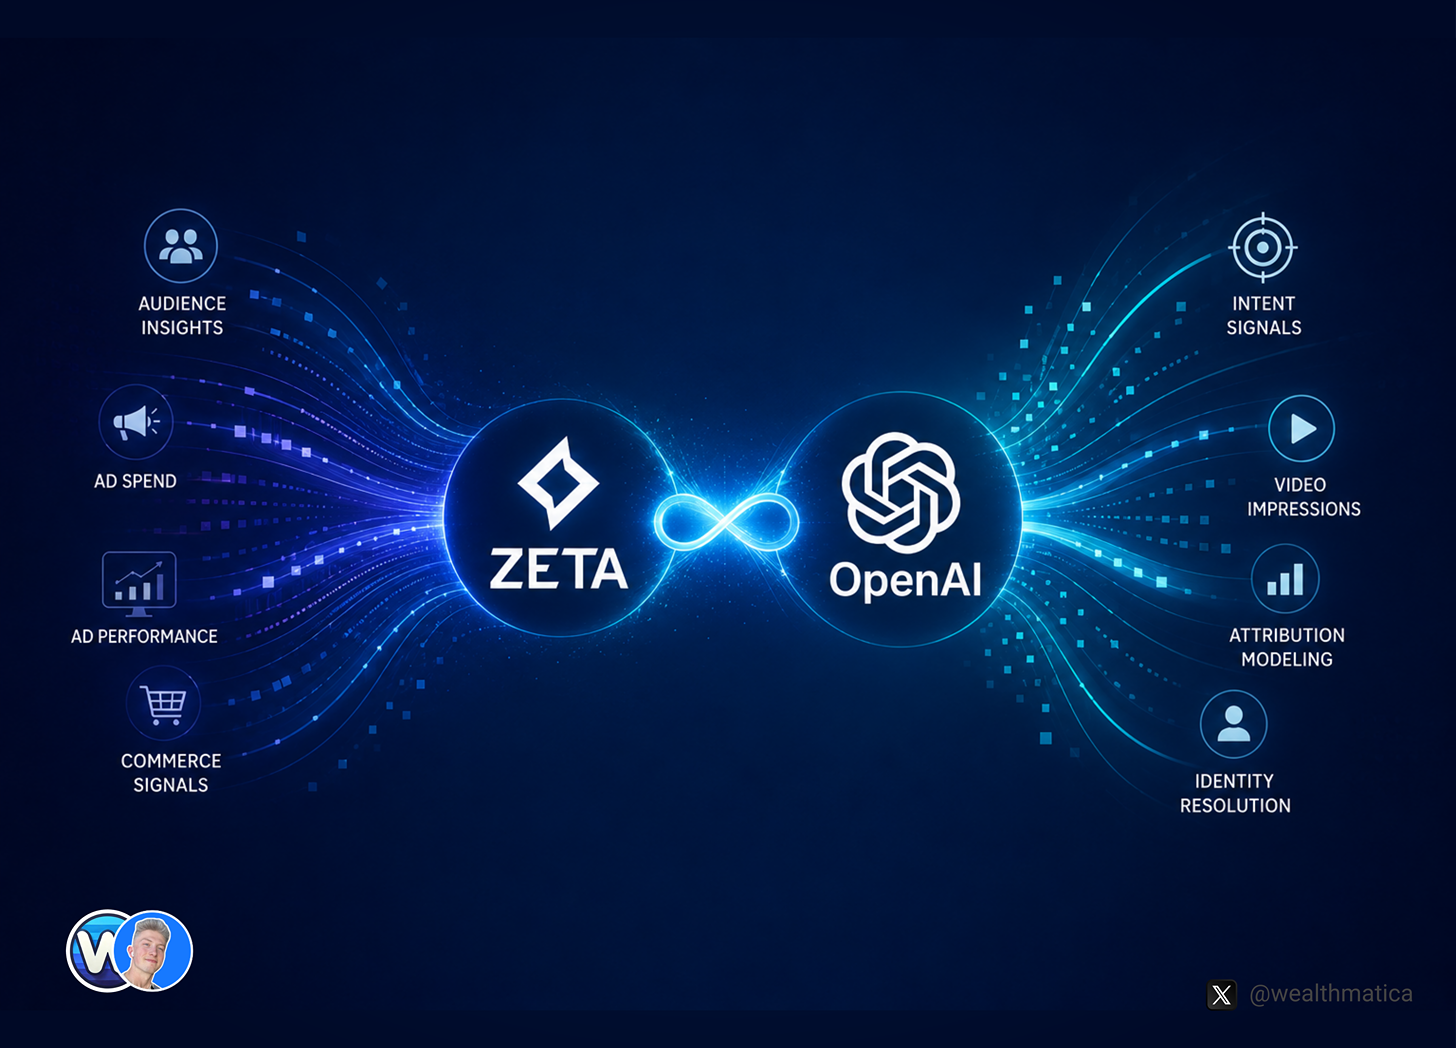
In reality, Zeta Global was the selected party to help fulfill enterprise ad-placement and GEO technology within the OpenAI ecosystem. This was confirmed by Zeta Global CEO David Steinberg in mid-May at the JPMorgan 54th Technology Conference:
“Well, I’m super excited to mention today that we have now executed an agreement to partner with OpenAI and help them run their advertising. We’re going to bring our enterprise clients into the OpenAI ecosystem, and we’ll begin to serve ads there on behalf of our enterprise clients.”
— David A. Steinberg, Co-Founder, Chairman & CEO of Zeta Global
So, you may be asking – why Zeta Global? You see, Zeta Global has developed a posture of agnostic integration. Instead of competing with the walled-gardens and social media platforms for their share of ad-dollars – why not work with them? Zeta Global has a robust partnership with Google and Meta that integrates Zeta’s ecosystem with the ad-placement ecosystem inside the walled-garden platforms of Youtube, Instagram, Facebook, etc. The result is an extremely accurate, high-resolution identity triangulation between:
The enterprise client customer data.
Walled-garden ecosystem data.
Zeta Global’s data.
It is highly likely that OpenAI recognized this value proposition and identified the immense strategic opportunity in partnering with an enterprise-ready, third-party intent/identity resolution platform like Zeta Global. Although, there has been no further announcement from the OpenAI team themselves, it has been verified by the CEO of Zeta Global that this information was certified for public release by the OpenAI team.
As for now, the OpenAI and Zeta Global teams continue to be integrated and working on building the future of this new walled-garden ecosystem.
“I think we’re all learning, including OpenAI, in the coming months and quarters, as to how this ecosystem’s going to evolve, we have a front row seat to it. So, not only are we there today, their engineers are working directly with our engineers, their business teams are working directly with our business teams to help understand where new opportunities evolve.”
— Chris Monberg, CTO of Zeta Global
However, for Zeta Global shareholders you should be asking yourself a serious question. Given the market appetite to acquire revenue generating properties upon IPO – at what point does Zeta Global become so pivotal to OpenAI’s success, that it would be a liability to let it operate outside of the grasp of managements control?
Food for thought.
Zeta Global Wins.
Building an advertising platform, let alone a full-fledged DSP – is a ridiculously complex and resource-intensive undertaking. As these companies approach IPOs at exceptional valuations, investors are likely to expect meaningful revenue generation from day one. With that in mind, I believe it's reasonable to infer that OpenAI's earlier statement may have been alluding to completing its DSP infrastructure before pursuing an IPO.
As for Zeta Global, they stand to gain – and gain a lot. An agnostic Zeta, is a durable Zeta. This is a line I’ll continue to repeat over time, why? It’s quite simple. The more channels Zeta can bring online, gives the enterprise further optionality. The more optionality, increases the likelihood enterprises are willing to spend their marketing budget within the Zeta ecosystem.
The longer the enterprise spends as a Zeta client, the more proprietary intelligence specific to that enterprise will be created. This intelligence data will consist of insights, strategies and micro level intent data all about the specific enterprise customer. If that enterprise were to leave and terminate their Zeta Global services – that enterprise would lose all of that proprietary intelligence. This is the ultimate flywheel lock-in mechanism.
In my view, an OpenAI approaching IPO is also an OpenAI preparing to unlock advertising across its ecosystem. That would make the company a fully validated activation channel within Zeta's platform – one where Zeta established an early foothold. The result is millions in enterprise ad-spend freshly allocated through Zeta’s new, exclusive, and shiny OpenAI activation channel.
Ultimately, if OpenAI wants Google-like economics, it will need Google-like advertising. So the answer is, yes – Zeta Global stands to benefit tremendously.
Thank you for taking the time to read this article. I hope you enjoyed, and found some value in my research and opinions. Remember, I am not an investment advisor, just a retail enthusiast.